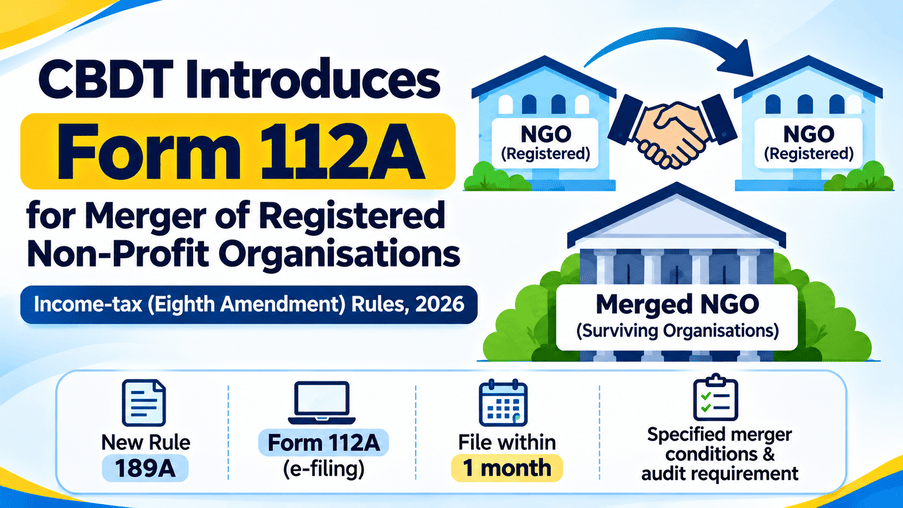
The Central Board of Direct Taxes (CBDT) has notified the Income-tax (Eighth Amendment) Rules, 2026, introducing Rule 189A and a new Form 112A. These provisions prescribe the compliance framework for mergers of registered non-profit organisations under the Income-tax Act, 2025.
The amendment aims to ensure that mergers of charitable and non-profit entities take place in a transparent manner while safeguarding tax compliance and protecting government revenue.
What is Rule 189A?
Rule 189A lays down the conditions that must be fulfilled when one registered non-profit organisation merges with another organisation having identical or substantially similar charitable objects.
The rule has been introduced to implement the provisions relating to mergers under Sections 352(4) and 354A of the Income-tax Act, 2025.
Introduction of Form 112A
CBDT has also prescribed Form 112A, which must be furnished electronically after completion of the merger.
The surviving organisation is required to submit the form to the jurisdictional Principal Commissioner of Income Tax (PCIT) or Commissioner of Income Tax (CIT).
Time Limit for Filing Form 112A
Form 112A must be filed within one month from the end of the month in which the merger takes effect.
Timely filing is essential for ensuring compliance with the newly prescribed rules.
Major Conditions for Merger
The newly inserted Rule 189A prescribes several important conditions, including:
- The organisations involved should have identical or substantially similar charitable objects.
- The merger framework distinguishes between regularly registered organisations and provisionally registered organisations and places restrictions where applicable.
- Outstanding tax liabilities and pending tax demands must be appropriately addressed.
- All assets, liabilities, rights and obligations relating to taxation should be transferred to the surviving organisation.
- The surviving organisation should continue to pursue the approved charitable objects.
- The objects of the surviving organisation cannot be changed for five years after the merger.
- Both organisations are required to get their accounts audited as on the date of merger.
These conditions are intended to ensure continuity of charitable activities and prevent misuse of tax exemptions.
Why Has CBDT Introduced These Rules?
Earlier, the Income-tax Act provided for mergers of registered charitable organisations, but a detailed procedural framework was not available.
The introduction of Rule 189A and Form 112A provides certainty regarding:
- eligibility for merger,
- transfer of tax obligations,
- audit requirements,
- reporting obligations, and
- post-merger compliance.
The amendment also facilitates better monitoring by the Income Tax Department.
Who Will Be Affected?
The new rules are relevant for:
- Charitable trusts
- Religious trusts
- Non-profit institutions
- Section 8 companies registered for charitable purposes
- Educational and medical institutions enjoying tax registration
- Other registered non-profit organisations covered under the Income-tax Act, 2025
Any organisation proposing a merger should carefully evaluate these requirements before finalising the transaction.
Key Takeaways
The introduction of Rule 189A and Form 112A marks an important compliance measure for the non-profit sector. Organisations contemplating mergers should ensure that all statutory conditions, audit requirements and reporting obligations are fulfilled within the prescribed time limits.
Proper planning before the merger can help avoid future disputes and ensure continued eligibility for tax benefits under the Income-tax Act, 2025.
Frequently Asked Questions (FAQs)
1. What is Form 112A?
Form 112A is the prescribed electronic form to be filed after the merger of eligible registered non-profit organisations.
2. Who has to file Form 112A?
The surviving organisation after the merger is responsible for filing the form.
3. What is the due date?
It must be filed within one month from the end of the month in which the merger becomes effective.
4. Is an audit mandatory?
Yes. Both organisations are required to have their accounts audited as on the date of merger.
5. Can the charitable objects be changed after merger?
No. The surviving organisation cannot alter its charitable objects for five years following the merger, subject to the conditions prescribed under Rule 189A.
Source: CBDT Notification No. 139/2026, G.S.R. 961(E), Income-tax (Eighth Amendment) Rules, 2026.
Related Article on Simple Income Tax
Buying Property Worth ₹50 Lakh or More? Here’s How to File Form 141
About the Author